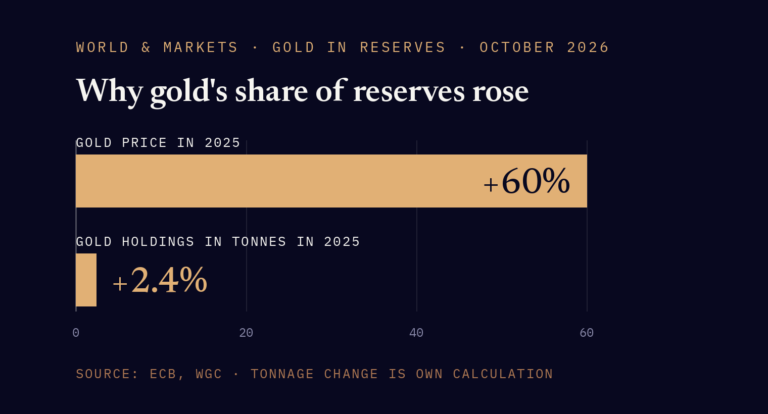Martin Filkuka · Brno · independent investor
Prices move every day.
Thinking about them shouldn’t.
This is my personal website. Instead of reacting to the daily noise, I take a long view and work with analytical discipline. I write about companies I study closely – whether I end up putting my own money into them or turn them down – and about the wider world those decisions sit in. Writing forces the thinking into order, gives it distance, and puts a date on it.
What I write about 04
- 01History, events and the meaning of money
- 02Psychology and investor behaviour
- 03Company analysis in depth
- 04Valuation and the mistakes in it
About
Martin Filkuka
I invest my own money. Not anyone else’s. I don’t give advice and I’m not trying to convince anyone. Everything here is my own decision, my own thinking or my own mistake. If someone asks what I think, I’ll gladly say – but the decision and the risk stay theirs.
I don’t forecast what the market does tomorrow. What interests me is why things move over the long run. That means reading financial statements, but just as much history, politics, psychology and how technology shifts underneath all of it.
The market sits at the very end of a long chain of events – and analysis that stops at the numbers has stopped too early.
I write about being wrong, too. Not out of performed humility, but because without the mistakes on the record, investing turns into a collection of success stories.
What it’s all for
I enjoy investing, but I don’t do it just to watch a number climb forever. Capital isn’t the goal, it’s the instrument – a way to support projects, ideas and people who deserve it and who make the world a little more worthwhile.
I’d rather be judged on what gets done than on what gets announced, so for now this is a direction rather than a detailed plan. It is, though, the reason to do the whole thing properly and with a long horizon.
Valuation
I don’t predict the price. I estimate the value.
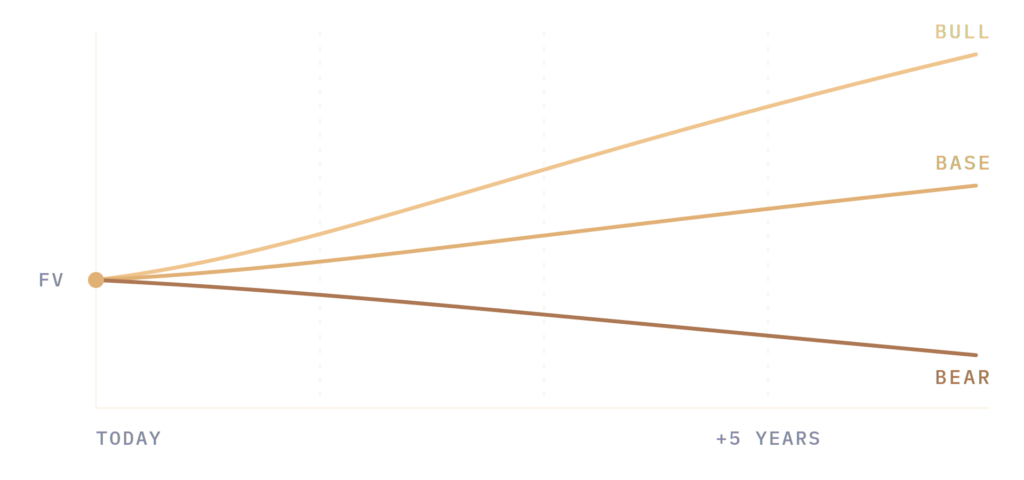
A price target is fortune telling, and I’m no good at it. Fair value is an estimate of what the business will generate for its owners over time. The uncertainty never goes away, so every company gets three scenarios: bear, base and bull.
What matters most is the spread between them. The wider it gets, the less I understand the business – and the smaller the position I can justify.
What gets calculated 03
- DCFDiscounted cash flow
- P/EEarnings multiple
- EVEV / EBITDA
Three routes to one answer. When they land near the same number, it’s a sign my assumptions hold together.
Process
Nineteen steps that can’t be skipped
- 01Key takeaways
- 02Business performance
- 03Financial quality and unit economics
- 04Management commentary
- 05Guidance and how to read it
- 06Risks, red flags and the bear case
- 07Capital allocation
- 08Insider buying and selling
- 09Competitive position
- 10Quality of the business
- 01Key takeaways
- 02Business performance
- 03Financial quality and unit economics
- 04Management commentary
- 05Guidance and how to read it
- 06Risks, red flags and the bear case
- 07Capital allocation
- 08Insider buying and selling
- 09Competitive position
- 10Quality of the business
- 11Hidden signals
- 12Valuation
- 13Base rates and comparable cases
- 14Expected return
- 15Portfolio fit
- 16Verdict
- 17Conviction
- 18Target weight
- 19Opportunity cost
Why step six? The hardest part of any analysis is naming the strongest argument against my own purchase – and writing it down before I reach a conclusion. Skip over that, and everything after it turns into a search for reasons I was right.
Writing
Analysis and context
Sometimes it’s a company I hold, sometimes one I worked through and passed on – and the second kind is usually the more interesting read. Alongside that: earnings commentary, introductions to businesses nobody writes about, and in between, pieces on current events, geopolitics or technology. The company work follows a fixed structure; the rest can’t and shouldn’t, because there the point isn’t the calculation but the connections. What they have in common is that you see the whole line of reasoning, not just the conclusion.
- All
- Companies
- World & Markets
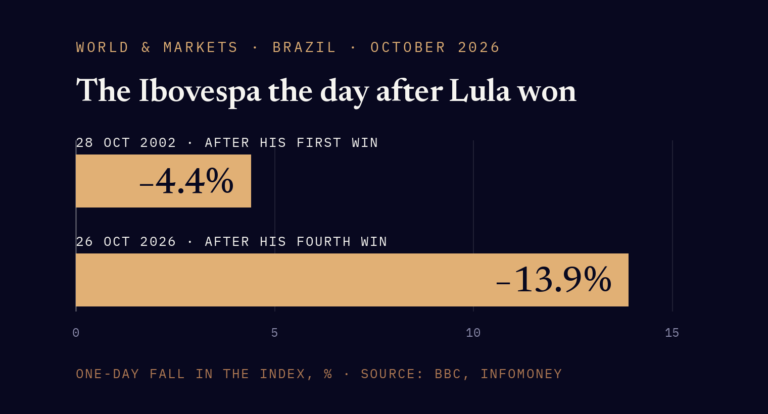
Brazil just had its worst day in six years....
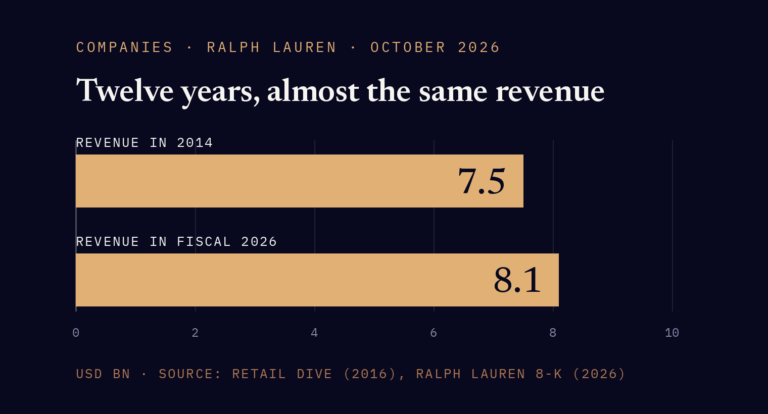
Ralph Lauren is a better company than ever. The...
Gold has overtaken US Treasuries. Central banks actually bought...
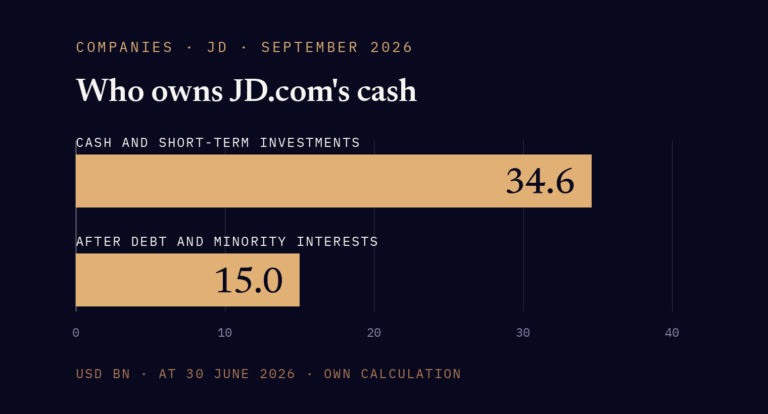
JD.com looks like a pile of cash with a...
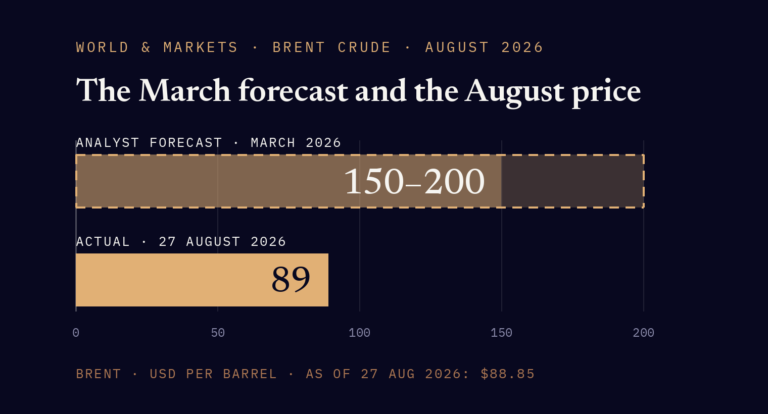
The worst case has lasted six months. Oil is...
Don’t miss the next piece
Check your inbox
I've sent you an email with a confirmation link. If it doesn't arrive within a few minutes, check your spam folder.
You’ll confirm the subscription through a link in your email. I use the address only to send you my own articles, never pass it on, and you can unsubscribe at any time with a single click.
Details are in the privacy policy.
Straight up
What isn’t here
A good deal of what the investing world sells is deliberately missing here. Some of it doesn’t work in practice, some of it skirts the rules, and the rest is marketing. Everything I write on this site is free and will stay that way. If a paid course or seminar ever appears, it will sit clearly alongside the writing, not in front of it.
- –Trading signals and buy-now tips
- –Paid access to my positions and trades
- –Investment advice in the regulatory sense
- –Promised returns or regular portfolio performance reports
- –Management of anyone else’s money
- –Testimonials nobody can verify
Contact
Where to find me
Short notes on what’s happening
My profile