Zeta Global reported its twentieth consecutive quarter of beating its own guidance and raising it. Revenue grew 44% to $443 million, the company again reported positive net income under US accounting standards, and the stock ran to a 52-week high within days. Fourteen analysts joined the call. Four of them asked about the Palantir partnership.
Nobody asked about the table on page 24 of the quarterly filing.
It is, I think, the most important thing Zeta has published this year – and what makes it interesting is that it argues against both camps at once.
How a 20.7% margin gets made
Start with what everyone saw. Zeta reported adjusted EBITDA of $91.7 million for the quarter, a margin of 20.7%, up 170 basis points year on year. That reads like a software business beginning to scale.
In the same quarter, the company recorded $52.1 million of stock-based compensation.
Which means 57% of that margin is a line item the company added back to itself. Across the first half the ratio is higher still – $105.1 million against $157.8 million of adjusted EBITDA, or 67%. Leave the add-back out and the margin is not 20.7%. It is 8.9%.
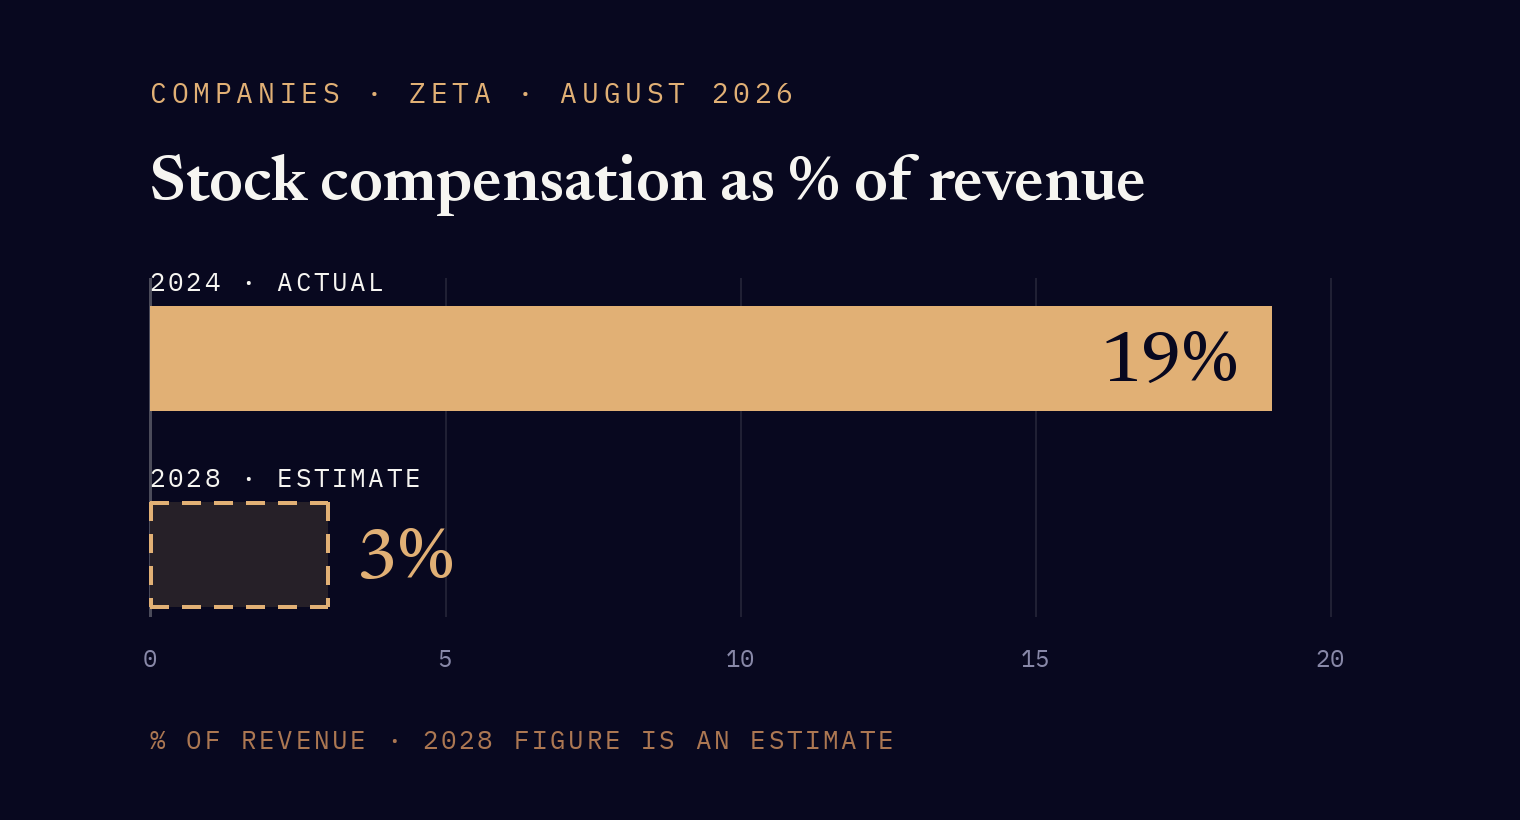
None of this is hidden. The full reconciliation sits in the filing line by line, and the practice is standard across American software. The difference is scale. At mature software companies stock compensation runs at low single digits of revenue. At Zeta it was 19% in 2024, 14% in 2025 and 11.8% last quarter.
The other side of the same coin is the overhang. Employees and management hold 12.0 million unvested restricted shares and units, 15.6 million performance stock units, and 15.1 million options struck at a weighted average of $13.50 – deep in the money. Together, 42.7 million instruments against 250.4 million shares outstanding. That is 17%, before the performance units pay out at up to 185% of target.
The table on page 24
Here is the part that got no airtime. The filing discloses stock compensation not yet recognised – expense already committed, waiting to land in future income statements. The total is $381.4 million, and it lands like this.
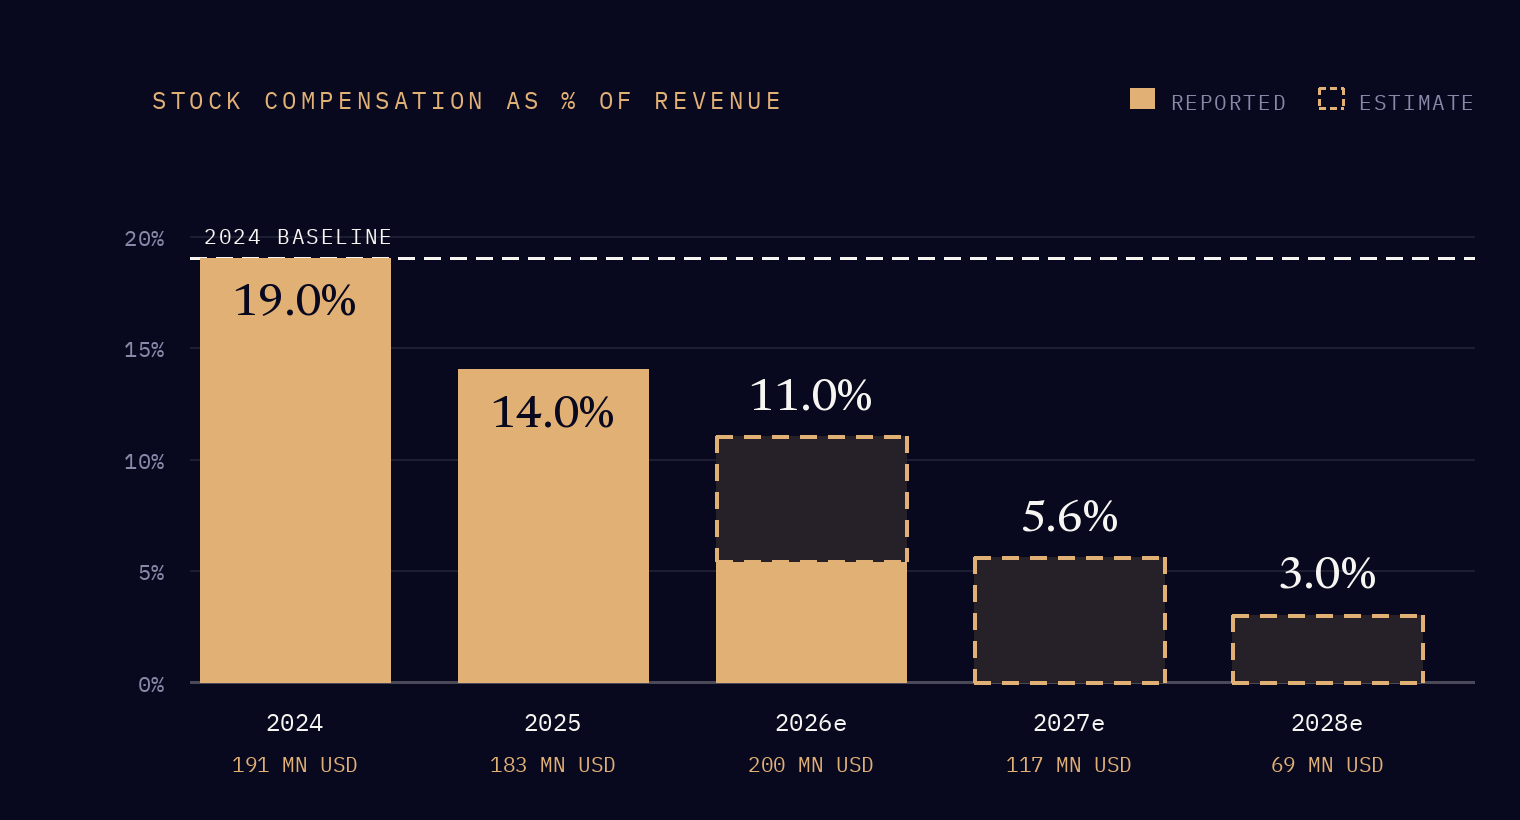
Add the $105 million already recognised in the first half and 2026 comes to roughly $200 million, or 11% of revenue. For 2027 the figure is $117 million – just under 6%, if revenue grows in line with the company’s own plan – and for 2028 it is $69 million, about 3%. (The percentages for 2027 and 2028 are my own calculation against estimated revenue, not figures published by the company.)
The schedule already includes the performance grant made in March, so this is not a rosy path built by omitting the last big tranche. Management also put a six-year incentive plan in place this spring that explicitly restricts further grants.
If it holds, the gap between adjusted and accounting profit largely closes inside two years – and with it goes the single strongest objection anyone can raise against Zeta today. It is not a certainty. The schedule covers existing awards, not future ones, and a promise to limit grants is a promise. But it is a specific, dated, published path, which is a different animal from an ambition.
Three questions nobody asked
- Contracted visibility is thin. Remaining performance obligations stand at $218.7 million for the next twelve months. Against full-year guidance of $1.818 billion, that is about 12%. Deferred revenue is $33.9 million and shrinking. Zeta describes itself as a system of record and an intelligent AI infrastructure layer, and it signed a multi-year agreement with Gap. But the overwhelming majority of revenue is volume-based, earned through usage rather than locked by contract. It recurs out of habit and results, which can be just as durable. It is not the same thing as subscription, and that is worth holding in mind before applying software multiples.
- Gross margin has fallen for four straight years, from 63.5% in 2022 to 59.5% over the trailing twelve months, with a 300 basis point decline last quarter. The mechanism is stated plainly in the filing: direct platform revenue slipped from 75% to 72% of the mix quarter over quarter, because new agency mandates begin in social channels. A meaningful share of incremental revenue is therefore media buying rather than software. Asked directly about the second half, the CFO did not promise a reversal – he said it depends on mix. That is an honest answer, and also not the answer you want inside a margin expansion story.
- One customer accounts for more than 10% of revenue and more than 10% of receivables, in both comparative periods. The company does not name it. On quarterly revenue of $443 million, losing that relationship would wipe out a substantial part of organic growth.
Valuation: expensive against what?
Zeta traded at around $29 on 11 August 2026, at a 52-week high, up roughly 55% over twelve months, at a market cap of $7.3 billion.
Valuing it three independent ways gives a 2027 range of roughly $24 to $28, with a weighted centre near $25.5. Discounted cash flow is the most generous of the three and lands close to the current price; the multiple-based approaches put fair value 14 to 18% below where the shares trade. (That range is my own calculation, not a consensus figure.)
The spread between the methods is not an error and should not be averaged away. It is a disagreement about duration: discounted cash flow prices a decade of growth, while multiples price one particular year at a multiple that is not permitted to expand. Both are legitimate questions, and the answers diverge depending on how much of the future you are willing to pay for today.
Which reduces the whole thing to one sentence: at this price you are paying more than the 2027 fair value, even on the most favourable method. Even if nothing goes wrong over the next two years, the stock can still disappoint. Any return from here has to come from something not yet in the numbers at all – partnership revenue from Palantir and OpenAI that management deliberately refuses to guide, or Zeta Business Intelligence, which as of today has no disclosed figures whatsoever.
That is a profile you can pay for. It is just worth knowing you are paying for it upfront.
Three things I would watch
Before I close the analysis I write down what would change my mind – and I write it now, not once I know the answer. Without that, a conclusion can always be bent afterwards to come out right. With Zeta it is three numbers.
Start with stock compensation. If it stays under 12% of revenue through the third and fourth quarters and tracks the published schedule downward rather than being refilled with fresh grants, then the strongest objection to this business is genuinely on its way out, and today’s accounting profile is a transitional state rather than a permanent one.
The second number is the direct platform mix. It slid from 75% to 72% in a single quarter; if that stops, the four-year decline in gross margin is a mix effect that has found its floor, rather than the shape of the business changing underneath the software narrative.
The third is organic growth. Excluding acquisitions and political advertising, anything meaningfully above the 23% the company has guided for the third quarter would suggest the conservatism built into that guidance is larger than it looks – which is the one thing that would make the current price defensible on this year’s numbers rather than next year’s.
Sources: Form 10-Q for the period ended 30 June 2026 and the earnings call transcript of 4 August 2026. My own calculations are labelled in the text. The author holds a position in Zeta Global.
The views expressed here are my own personal opinions and reflect my own portfolio decisions. This content is for informational and educational purposes only – it is not investment advice, a recommendation, or a solicitation to buy or sell any security. Always do your own research or consult a licensed financial advisor before making investment decisions.