BioMarin’s second quarter sent the stock up 16% in three trading days. Revenue rose a fifth to $990 million, earnings beat expectations by a quarter, and the company raised full-year guidance. On the face of it, a clean quarter.
The more interesting question is the one the headlines don’t ask: which part of the guidance went up?
The number that didn’t move
BioMarin raised the midpoint of its total revenue range by $25 million. It also raised the midpoint for VOXZOGO – its achondroplasia drug – by exactly $25 million.
The metabolic conditions segment was left unchanged. Right below the table, the company states that the raise reflects expectations for both segments. The table one line above says one of them didn’t move.
That would be unremarkable if this segment weren’t where this year’s Amicus acquisition sits. BioMarin bought Amicus in April, and with it Galafold and Pombiliti + Opfolda. The slide presenting them is titled “Acceleration Underway.” The company attached peak revenue targets of $1.4 billion and $1.2 billion and a decade-long plan.
Yet the outlook for the segment those drugs sit in is the same as it was in May – even though they will contribute two full quarters in the second half instead of two months.
There are two possible explanations. Either management is being cautious and keeping room. Or the acquisition is tracking exactly to plan and has produced no upside surprise. Neither is bad news. But neither matches the word “acceleration,” and it is worth knowing that the entire guidance raise rests on a single product – the one that faced its first competitor this year.
What the second half has to deliver
Split the guidance into what is already banked and what still has to arrive, and the back half of the year looks tight.
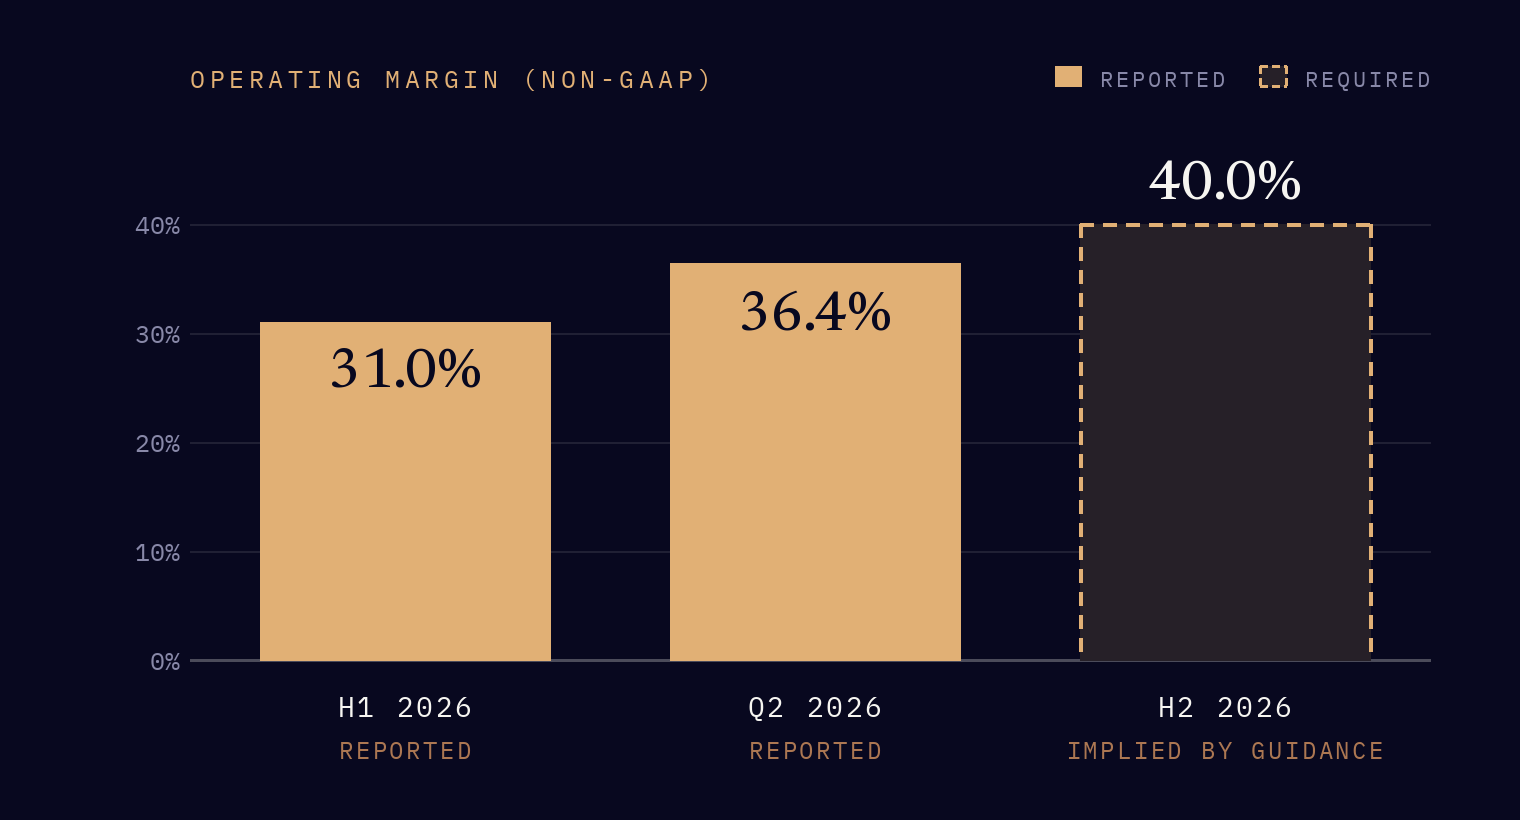
The first half produced roughly $1.76 billion in revenue and $545 million of operating income on the company’s own adjusted basis. For the midpoint of full-year guidance to hold, the second half has to deliver about $2.14 billion – 22% more than the first half – while growing profit by roughly 60%.
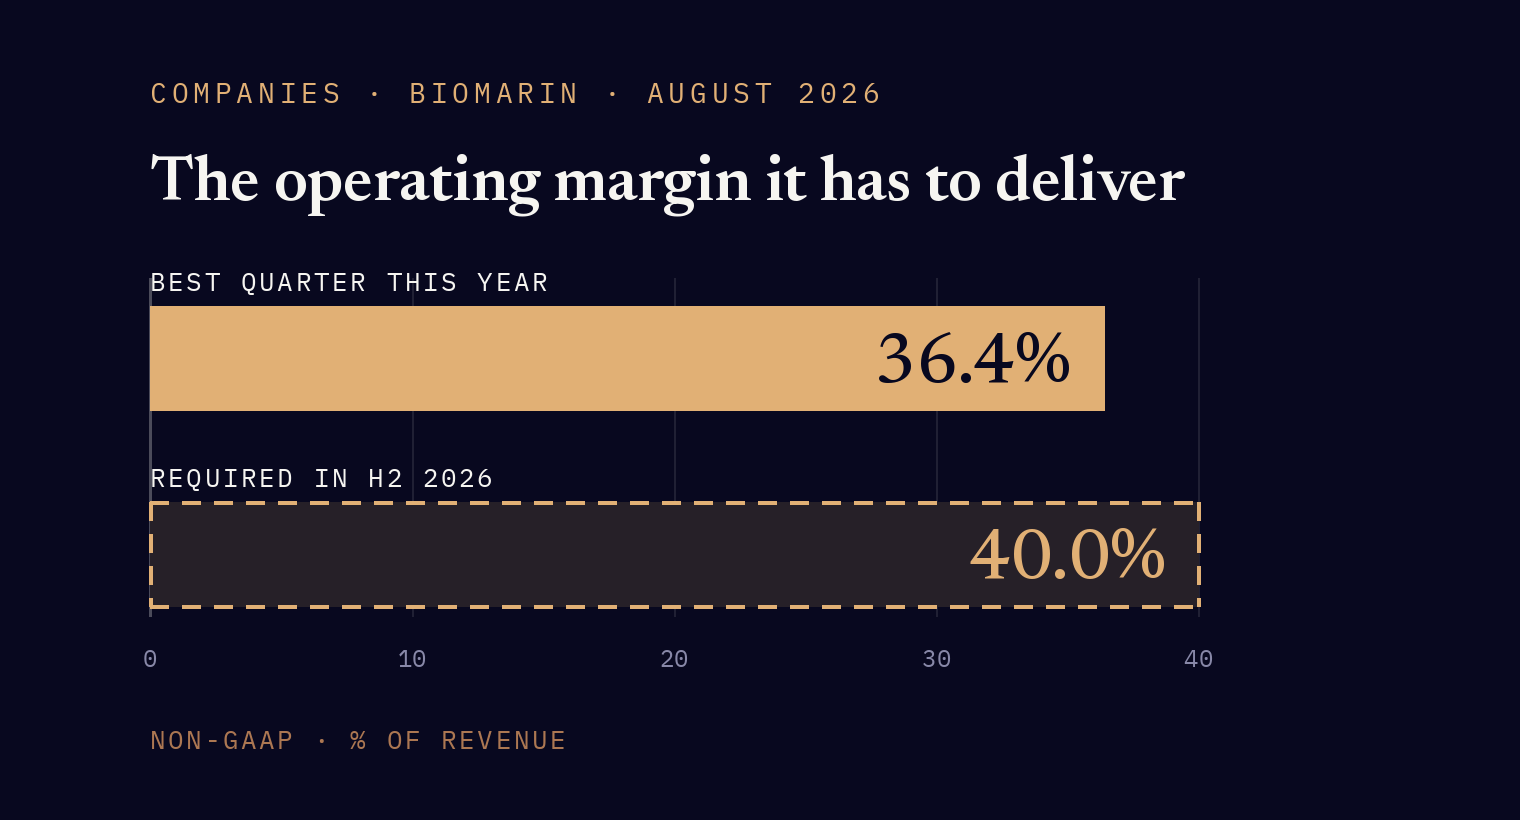
That implies an operating margin near 40%. The second quarter came in at 36.4%; the first half as a whole at 31%. (Those last two paragraphs are my arithmetic from company guidance, not a reported figure.)
It isn’t impossible. The company says the fourth quarter should be the strongest of the year. But the acquisition savings, on its own schedule, don’t ramp fully until 2028 – so they only partly help this year’s second half. 70% of those savings sit in general and administrative costs – historically the category that actually gets delivered, unlike “revenue synergies,” which are mostly wishful thinking.
But it is a commitment, not a result. The trend is running the other way: operating margin fell 3.5 points year over year in the second quarter, and by almost seven points across the first half.
Growth that measures a recovery
The headline slide shows earnings per share up 59%. In small print beneath the same slide, the company notes that last year’s base included a write-off of acquired research from the Inozyme deal and an inventory write-down on ROCTAVIAN, a drug it pulled from the market.
So the 59% largely does not measure operating performance. It measures how far the company climbed off a base it depressed itself with one-time charges. I’d put the underlying growth closer to 25% or 30% – still a good number, just a different one.
A similar asymmetry appears elsewhere in the same deck. The company sized its acquisition savings at $280 million under US accounting standards and $220 million on its own adjusted basis. The $60 million difference is stock-based compensation. Stock-based compensation counts toward the savings under accounting standards. It doesn’t count against profit on the company’s own basis.
None of this is improper or unusual – the whole sector does it. But it is worth knowing that the gap between accounting profit and company-adjusted profit at BioMarin was fivefold in the second quarter: $0.23 per share against $1.20. For the first half, $0.77 against $1.96.
A competitive test that can’t be graded for a year
In February, VOXZOGO faced a US competitor for the first time. Over five months, the company says about 10% of American patients switched – fewer than a hundred people. The other 90% stayed.
Management presents this as proof of a defended position, and it has arguments: five years of clinical data, exclusive approval for children under two, and the support wrapped around each patient. The reason for switching, the company says, isn’t efficacy but fatigue with daily injections.
But 10% over five months isn’t a departure from the usual pattern – it is the usual pattern. When an established drug meets its first competitor, erosion typically runs 10% to 20% of share per year for three or four years (my own estimate from a general pattern, not a figure from a specific study). A 90% retention rate after five months is the expected point on that curve, not evidence the curve doesn’t apply.
The answer arrives in three or four quarters at the earliest. Until then, any claim about a “defended position” – mine or the company’s – is premature.
Cheap against what?
BioMarin trades at roughly fourteen times this year’s expected adjusted earnings. Its historical median sits somewhere near fifty. That looks like an enormous discount.
It isn’t. That median comes from years when the company was barely profitable – and when the denominator is close to zero, any multiple comes out astronomical. Comparing today’s fourteen against a historical fifty is like comparing a temperature against one taken with a broken thermometer.
A simpler comparison is more useful: fourteen times earnings and about twelve times EBITDA are in line with what the market pays for comparable companies. Not a premium, but not a discount either. Anyone buying today isn’t betting the market will re-rate the stock upward. They’re betting the numbers show up.
Which is the whole thesis in one sentence: there is very little upside left in this year’s numbers, but real upside in next year’s – provided the second half delivers the margin the guidance implies.
Three things I’d watch
I write down in advance the conditions that would change my mind, while I still don’t know the outcome. Otherwise any conclusion can be adjusted after the fact. For BioMarin it comes down to three numbers.
Start with the margin. If the margin in the third quarter, which the company reports on 27 October, clears 36.5% and the fourth quarter follows through, the tight guidance was realistic and my caution was misplaced.
Next, patient numbers. Should the count of children treated with VOXZOGO still be growing at a double-digit rate a year from now despite the competitor, the clinical data are a stronger defence than the usual pattern would suggest.
The savings come last, and they matter most. If at least half are realised during 2027, as the 2028 schedule implies, that would be the best news of all – because large debt-funded acquisitions historically don’t come apart in the first quarter. They come apart somewhere between the twelfth and the eighteenth month.
Amicus closed at the end of April. That window opens next spring. One good quarter is not evidence that the usual pattern doesn’t apply – it is exactly what the typical case looks like in quarter one.
Sources: the company’s earnings presentation and conference call transcript, 6 August 2026. My own calculations are labelled in the text. The author holds a position in BioMarin.
The views expressed here are my own personal opinions and reflect my own portfolio decisions. This content is for informational and educational purposes only – it is not investment advice, a recommendation, or a solicitation to buy or sell any security. Always do your own research or consult a licensed financial advisor before making investment decisions.